From Ops Rooms to Living Rooms: How Humanoid Makers Reframe Value for Logistics Chiefs, Hospital CIOs and Homebuyers (2025–26)
Executive summary Humanoid robotics marketing in 2025–26 has bifurcated into two narratives: aspirational R&D storytelling that attracts press and investor capital, and hard-nosed, verticalized go-to-...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
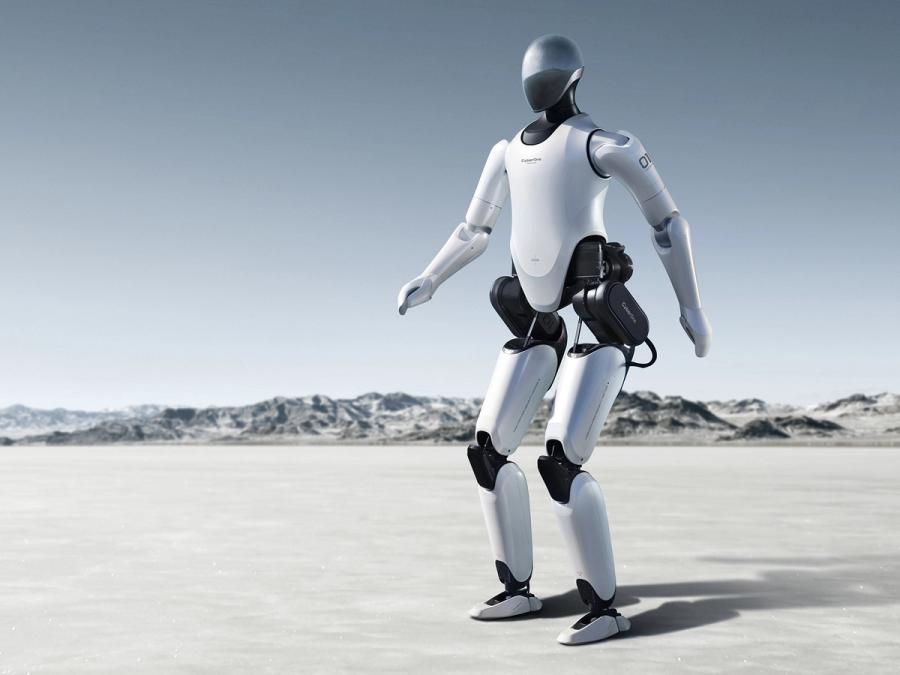
Executive summary Humanoid robotics marketing in 2025–26 has bifurcated into two narratives: aspirational R&D storytelling that attracts press and investor capital, and hard-nosed, verticalized go-to-market (GTM) playbooks that win paid pilots and scale. Leading vendors purposefully dress the same underlying technologies in different suits for logistics operations managers, manufacturing integrators, hospital procurement offices and retail shoppers. This article maps those playbooks — direct enterprise sales, system-integrator partnerships, Hardware-as-a-Service (HaaS) pilots, and consumer bundling — and explains how messaging, demo formats, pricing and partnership choices change by buyer persona. How vendors translate product into vertical value Humanoid makers do not sell the same thing to everyone. The product story is reframed to match the buyer’s KPI set: Logistics (Agility Robotics, Figure AI) — throughput, uptime, and predictable fill-rate. Messaging centers on picks-per-hour, 24/7 operation and integration with warehouse management systems (WMS). Manufacturing (Apptronik, Fourier Intelligence) — repeatability, cycle-time reduction and safety in collaborative environments. Emphasis is on deterministic motion, safety cages/instrumentation and integrator-friendly APIs. Healthcare/eldercare (Sanctuary AI, 1X Technologies) — compliance, privacy, and empathetic interaction. Marketing leans on HIPAA-readiness, caregiver augmentation and risk mitigation for clinical workflows. Consumer/lifestyle (Xiaomi CyberOne, UBTECH) — personality, convenience and content/ecosystem. Consumer messaging focuses on companion features, app ecosystems and retail experience. Use cases and industries Parcel sorting and piece-picking in e-commerce and third-party logistics (3PL). Parts kitting, line-side supply and light-assembly in automotive and electronics factories. Patient transport assistance, telepresence and cognitive support in hospitals and eldercare homes. Home companionship, education, and lifestyle augmentation for high-end consumers and fan communities. Vendor playbooks: sales channels and pricing models Humanoid vendors use four main GTM vehicles, often mixed together: Direct enterprise sales — favored by vendors with deep integration requirements (e.g., manufacturing automation). Sales cycles are long, proof-of-concept (PoC)-heavy and driven by in-house field teams and engineering support. System-integrator (SI) partnerships — common in factories and hospitals. Apptronik and Fourier emphasize certified integrator networks to reach automation OEMs and medical device integrators. Hardware-as-a-Service (HaaS) pilots — widely used for logistics rollouts: vendors lease units, absorb initial integration risk and charge per-uptime or per-task. This converts capital expenditure resistance into an operational expense. Consumer retail bundling — UBTECH and Xiaomi rely on channel retail, online marketplaces and ecosystem services to scale non-enterprise units priced for mass markets. Pricing context: Commercial, enterprise-grade humanoids and integration projects are typically positioned in the high-five to low-six-figure range per robot plus software and integration fees. HaaS pilots often run from a few thousand to tens of thousands per month per unit, depending on SLA and support scope. Consumer-facing humanoids are positioned well below enterprise units — low four-figures to mid-five-figures — and rely on software/consumer services revenue to improve margins. Demo formats, trade shows and certification narratives How a robot is presented at a trade show or in an on-site demo is intentionally tailored: Ops-room demos for logistics chiefs — live, timed pick-and-place runs adjacent to dashboards showing picks/hour and mean time between failures. Vendors overlay site-specific ROI calculators showing payback in 12–24 months under common labor-cost scenarios. Integrators and line supervisors — “hands-on kit” demos where an SI integrates a robot onto a test cell in a day; certified safety packages and ISO/ANSI compliance dossiers are provided upfront. Healthcare decision-makers — clinical-simulation labs with privacy red-teaming, redacted data flows and whitepapers on HIPAA, risk and infection control. Vendors supply third-party safety and medical-equipment compatibility reports. Retail and consumer experiences — walk-up interactions, app-driven personalization demos in flagship stores and AR/VR trial apps that simulate in-home behaviors. “We stop selling the robot and start selling a supervisor dashboard, a labor-savings model and a 90-day SLA,” industry marketing leads told us when describing logistics pilots. That shift is what converts demos into paid PoCs. Pilot terms and case-study storytelling Typical pilot contracts for enterprise buyers include: 90–180 day PoC with clearly defined success metrics (throughput delta, error rate, uptime). HaaS monthly fees that convert to purchase credits if deployment scales. Limited indemnities, with post-pilot pricing adjusted for custom integration scope. Successful customer storytelling follows a pattern: quantify baseline KPIs, show post-deployment delta, outline the path to scale. Vendors that expose raw telemetry and a clean ROI model win credibility. In logistics, for example, Agility and Figure-style vendors tout improvements in picks-per-hour and reductions in overtime spend; in manufacturing, Apptronik-style stories emphasize cycle-time tightness and reduced rework. Competitive comparisons (select) Company Primary vertical GTM playbook Pricing posture Demo & compliance emphasis Agility Robotics Logistics, fulfillment HaaS pilots + enterprise sales Enterprise pricing; HaaS options Ops-room throughput demos; WMS integrations Figure AI Logistics, factories Direct + SI partnerships Enterprise; ROI calculators for ops execs Factory floor cell demos; uptime SLAs Apptronik Manufacturing, systems integrators Integrator-led deployments Project-based pricing Line-side safety packages; ISO/ANSI narratives Sanctuary AI / 1X Tech Healthcare, eldercare Hospital partnerships, clinical pilots HaaS or capital sale + service Clinical simulation, HIPAA whitepapers Xiaomi CyberOne / UBTECH Consumer, lifestyle, education Retail channels, app ecosystems Consumer pricing tiers Retail demos, personality-driven UX Creative marketing tools that convert procurement to pilots Three categories of creative assets consistently move conversations forward: ROI calculators and TCO models — downloadable tools tailored to warehouse and line managers that convert abstract throughput claims into payback timelines. Logistics vendors often provide templated spreadsheets that insert local labor rates and hours to show a 12–24 month payback. Compliance and safety bundles — whitepapers, third-party test certificates and prebuilt safety integrations for medical and factory buyers. Hospitals demand documentation around data flows and infection control before a trial is scheduled. Consumer-facing apps and retail experiences — personalization flows, companion services and subscription add-ons that make a home robot feel like a platform, not a gadget. Contrast: aspirational PR vs. focused GTM There is a strategic tension across the industry. Tesla and Boston Dynamics lean heavily on aspirational PR: bold long-horizon visions and dramatic demos that attract mainstream attention. Those narratives are powerful for fundraising and brand-building but do not, by themselves, win factory floor purchase orders. Conversely, vendors such as Apptronik and companies focused on logistics adopt a far more prosaic commercial GTM: certified SI relationships, metrics-driven demos, and pilot economics. That focus produces traction with procurement committees and operational buyers. What converts into paid pilots and scaled contracts Interviews with marketing leads, channel partners and procurement officers reveal consistent conversion triggers: Clear, measurable PoC success metrics and short pilot durations (90–180 days). Low-friction integration paths — prebuilt WMS/PLC connectors and SI-led installations. Commercial models that shift first-mover risk to the vendor (HaaS, uptime-linked fees). Regulatory and safety documentation for clinical and industrial buyers. Conclusion Humanoid robotics vendors are learning that one-size-fits-all storytelling fails. Successful firms tailor language, channels and experiential assets to the buyer: reliability and throughput for logistics, repeatability and safety for manufacturing, compliance and empathetic interaction for health systems, and personality and ecosystem for consumers. The companies that combine credible pilots, integrator networks and practical ROI tools will turn press-friendly visions into scaled commercial deployments over the next 24–36 months.