Pitching the biped: how humanoid robotics companies tailor marketing, channel and product stories for warehouses, wards and living rooms
Executive summary Humanoid robotics vendors are not selling the same dream. Across Tesla (Optimus), Boston Dynamics (Atlas/Spot), Agility Robotics, Figure, Apptronik, 1X, Sanctuary AI, Fourier, Xiaomi...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
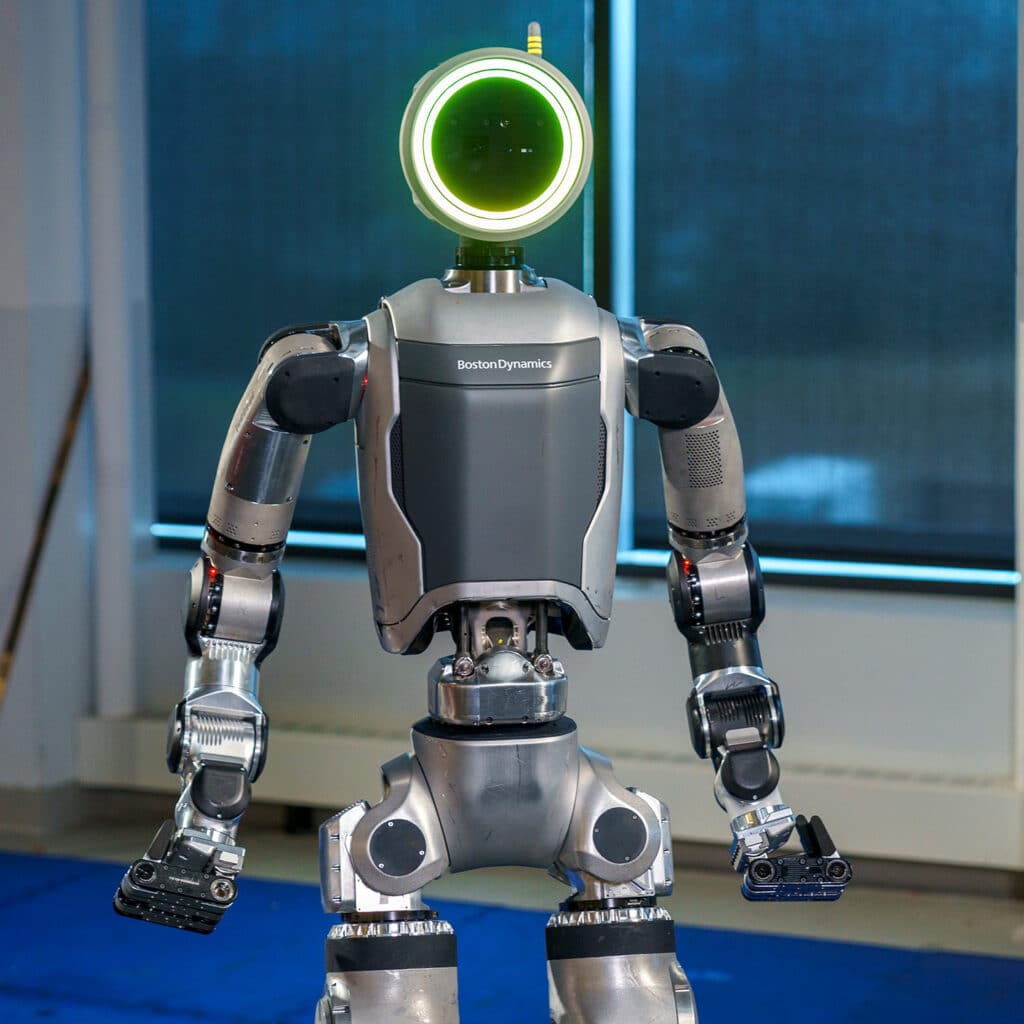
Executive summary Humanoid robotics vendors are not selling the same dream. Across Tesla (Optimus), Boston Dynamics (Atlas/Spot), Agility Robotics, Figure, Apptronik, 1X, Sanctuary AI, Fourier, Xiaomi, UBTECH and Unitree, commercial narratives split along clear buyer personas: scale-and-cost disruption, R&D prestige, logistics ROI, factory safety/integration, regulated‑care compliance, and consumer/light‑service demos. Each company pairs a product story with specific channel tactics — enterprise partnerships, system integrators, pilot-to-contract funnels, managed services, or developer ecosystems — to translate the novelty of a biped into buyer economics. Below I dissect the main narratives, concrete tactics and what procurement teams should watch for through 2025–26. Positioning spectrum: from scale disruption to prestige R&D The market divides into a handful of archetypes: Scale-and-cost disruption — Tesla’s Optimus messaging: apply Tesla manufacturing scale, in‑house AI and Dojo compute to drive down unit cost and offer an automation alternative to low‑skill labor. R&D prestige and capability showcase — Boston Dynamics’ Atlas remains demonstrative: high‑visibility parkour and dexterous demos that signal technical leadership rather than immediate productization; meanwhile Spot is commercialized as a field inspection tool. Logistics ROI — Figure and Agility emphasize pick-and-place and last‑mile warehouse tasks, using ROI calculations (picks per hour, uptime, labor substitution) as the primary sales story. Factory safety and integration — Apptronik and 1X pitch humanoids as safer, compliant, integrable systems for repetitive assembly and machine tending, stressing ISO/ANSI standards and collaborative robot (cobot) compatibility. Regulated healthcare / eldercare — Sanctuary AI and companies like Fourier (and other medical robotics firms) position around compliance, clinical validation and care‑workflow integration. Consumer / light‑service demos — Xiaomi, UBTECH and Unitree present lower‑cost, entertainment-and-service use cases for homes and hotels to build awareness and accelerate adoption of “good enough” capabilities. Why the split matters Buyers, from COOs to hospital administrators, respond to different value levers. Logistics managers measure picks/hour and throughput; plant managers care about safety, downtime and MES/PLC integration; healthcare procurement requires regulatory documentation, trials and liability frameworks; consumers and hotel operators prioritize price and experience. Vendors tune their messaging and their go‑to‑market stack accordingly. Concrete tactics: how firms translate narratives into deals Across companies the same toolbox is deployed differently: Enterprise partnerships & system integrators: Logistics‑focused vendors emphasize partnerships with conveyor, WMS and material‑handling vendors so a humanoid can be sold as a module inside a broader automation solution. Manufacturing vendors partner with integrators to supply safety fencing, PLC interfaces and risk assessments. Pilot‑to‑contract funnels: Typical sales pattern: 3–6 month pilot (site assessment, small fleet, KPI targets) → performance-based SLA → multi‑unit roll‑out. Vendors in logistics publish pilot metrics (reduced manual lifts, picks/hour) to shorten procurement cycles. Managed services and revenue models: To mitigate buyer capital risk, some vendors offer managed fleets or robotics‑as‑a‑service (RaaS) pricing. This is especially common in hospitality and light‑service segments where operators prefer per‑usage fees over CapEx. Channel vs direct sales: High‑touch, regulated verticals (healthcare, manufacturing) favor channel partners and systems integrators; consumer and demo‑oriented companies lean on direct channels and retail showrooms. Developer ecosystems and SDKs/APIs: Vendors courting long‑term platform adoption invest in SDKs and developer programs. Tesla, for instance, frames its autonomy stack and compute platform as an eventual developer play; logistics vendors provide WMS APIs and ROS‑compatible stacks to accelerate integration. Demo centers and public showcases: High‑visibility demos (trade shows, AI days, hotel pilots) serve distinct purposes: Tesla and Boston Dynamics use spectacle to cement brand leadership; UBTECH/Xiaomi use hotel and consumer showcases to validate real‑world service interactions. Marketing collateral, pilots and pricing cues Marketing tends to emphasize the metric that matters to the target buyer: Logistics case studies — Agility/Figure style collateral highlights picks/hour, fill‑rate improvement and labor substitution percentages. Pilot case studies typically show 15–40% labor reduction targets during optimized workflows (vendor‑reported). Factory integration docs — Apptronik/1X materials lean on safety certifications, MTBF figures and integration timelines (weeks vs months) to reassure plant managers. Healthcare messaging — Sanctuary and Fourier publish compliance roadmaps, clinical trial plans and interoperability with EHR and nurse workflows to address liability and reimbursement questions. Pricing cues — Price transparency varies: Boston Dynamics lists Spot pricing publicly (around high five‑figures for a single unit with service contracts); Unitree’s quadrupeds offer sub‑$10k research units. For humanoids, most vendors keep pricing indicative or subscription‑based until pilots validate ROI — a signal that buyers should expect software, integration and service to dominate TCO. Competitive comparisons (compact) Company Primary pitch Buyer persona Channel & sales tactic Tesla (Optimus) Scale and cost disruption via in‑house AI & manufacturing CxOs focused on long‑term labor economics Direct, brand-driven; public demonstrations to seed demand Boston Dynamics (Atlas/Spot) Technical leadership; Spot commercialized for inspections Industrial inspection, R&D teams Direct sales + channel for Spot; PR and demos for Atlas prestige Agility / Figure Logistics ROI: picks, throughput, uptime Logistics & supply chain execs Pilots → ROI case studies; WMS integrator partnerships Apptronik / 1X Factory safety and integrability Plant managers, safety officers System integrators, certification documentation Sanctuary / Fourier Care and clinical compliance Hospital administrators, regulated‑care buyers Clinical pilots, regulatory pathway transparency Xiaomi / UBTECH / Unitree Consumer & light service demos Hotel operators, consumers, hospitality tech buyers Showrooms, hotel pilots, retail channel Implications for buyers: reading the marketing Procurement teams must triangulate three signals before committing: Operational metrics vs spectacle: Separate show‑video gloss from production metrics. Public demos (parkour, humanoid runs) prove capability edges but not uptime, maintenance or TCO. Pilot KPIs and integration scope: Insist pilots include measurable KPIs (throughput, downtime, safety incidents) and a clear integration plan that maps to PLCs, WMS or EHR systems. Ask for failure modes and manual fallback procedures. Commercial model and lifecycle costs: Clarify whether price is unit CapEx, subscription, or managed service. Many vendors hide service and integration costs until after pilots; expect these to dominate early TCO. Marketing will continue to diverge: spectacle and scale narratives win headlines, but verticalized ROI, safety integration and regulatory compliance will win budgets. Outlook to 2025–26 Expect a bifurcated near term: logistics and factory narratives — where ROI can be modeled and inked into SLAs — will drive the first meaningful commercial rollouts. Hospitality and consumer demos will proliferate as lower‑cost platforms prove repeatable experiences. High‑visibility players leaning on scale (Tesla) and prestige (Boston Dynamics) will shape brand perceptions, but buyers seeking replaceable labor or safety‑certified automation will favor vendors that come with integrator networks, clear pilot metrics and managed service options. For hospital and eldercare markets, vendors that invest in clinical validation and regulatory pathways will be the ones procurement teams can trust. Bottom line for buyers: match the vendor narrative to your persona. If you are buying throughput, demand ROI and integrator commitments. If you are buying compliance, demand trials and regulatory evidence. If you are buying future optionality, weigh brand scale and developer ecosystems — but budget for integration and service above sticker price.