Scale Wars: Why Manufacturing Capacity, After‑Sales Support and Supply Chains Will Decide the 2026 Humanoid Winners
Executive summary By the end of 2026 the humanoid landscape will not be decided by the most convincing demo video but by a narrower set of commercial levers: manufacturing throughput and true COGS, co...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
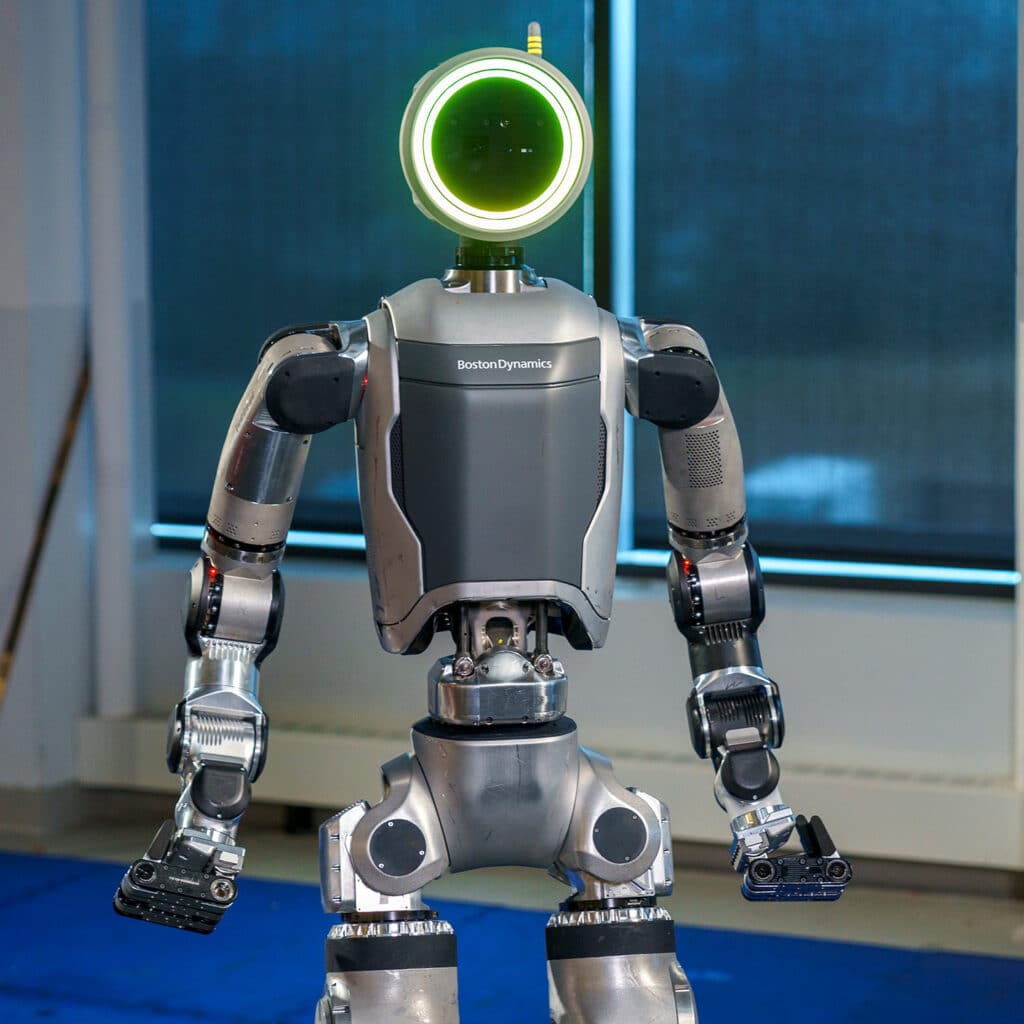
Executive summary By the end of 2026 the humanoid landscape will not be decided by the most convincing demo video but by a narrower set of commercial levers: manufacturing throughput and true COGS, component supply security for key actuators and batteries, the cost and responsiveness of field service, and recurring aftermarket revenue that converts pilots into sustainable economics. Firms that combine either deep vertical manufacturing (Tesla, Xiaomi) or highly optimized service-and-software stacks (Boston Dynamics, Agility) will be best positioned to scale. Startups that rely on third-party contract manufacturers and fragile actuator supply chains face a narrow runway unless they lock in recurring ARR and integrator partners quickly. Manufacturing throughput and COGS: vertical integration vs outsourcing Humanoid margins are driven by high part counts and tight tolerances. Tesla and Xiaomi publicly emphasize in‑house manufacturing, tooling and battery supply — a familiar playbook for lowering per‑unit COGS as volumes rise. That gives them two advantages: the ability to iterate hardware quickly and to push down BOM cost through internal economies of scale (EV and consumer electronics supply chains respectively). Most startups — Figure, Apptronik, Sanctuary, 1X Technologies — are outsourcing assemblies to contract manufacturers (CMs) or white‑box houses. Outsourcing lowers initial capital burden but exposes companies to: longer lead times for board/PCBA runs and harnesses, less leverage to reduce unit cost as volumes grow, and higher quality control overhead and warranty exposure if CM yields lag. Implication: a firm that can cut COGS by 30–50% as volumes move from tens to thousands of units will undercut competitors on price-to-service ratio and capture enterprise fleet deployments. Expect Xiaomi and Tesla to use this lever most effectively; expect Unitree and UBTECH to compete on low BOM cost through existing scale in China. Component supply risks: actuators, motors, sensors and batteries Robust supply of custom actuators, high‑torque motors, lidar/vision stacks and batteries is a gating factor. Several patterns matter: Custom actuators: Apptronik, Figure and Boston Dynamics depend on bespoke actuators for torque density and thermal management. These are not commodity parts — tooling and supplier qualification take months and capital. Motors and powertrains: 1X Technologies sells modular actuators and is both a customer and competitor — its supply decisions ripple across multiple integrators. Sensors and batteries: firms with existing battery supply (Tesla) or smartphone/consumer electronics clout (Xiaomi, UBTECH via BBK ecosystem) reduce exposure to shortages and pricing shocks. Supply concentration (single actuator supplier, single battery pack) is a risk that will manifest as delayed rollouts or spiked warranty costs in 2025–26 unless hedged with dual suppliers or long‑term contracts. Service networks and field maintenance economics Robotic uptime is determined less by algorithmic autonomy than by spare‑parts availability, maintenance crew density and remote monitoring tools. Field maintenance economics split into: spare parts stocking (motors, joint modules, harnesses), MTTR from remote diagnostics and field technician dispatch, and software tools for predictive maintenance and warranty management. Companies with established service channels (Boston Dynamics has an authorized partner network for Spot and Stretch; Unitree and UBTECH operate large support channels in China) can deliver faster SLAs at lower marginal cost. Agility has explicitly targeted logistics customers with a serviceable, replaceable design (Digit), making field maintenance a competitive advantage in warehouses where downtime costs are quantifiable. “You buy robots for productivity but you keep them for uptime.” — a logistics CIO involved in early humanoid pilots. Aftermarket revenue models and pricing strategies Upfront price is only part of the picture. Commercial scale will favor business models that convert capital expenditure into dependable recurring revenue: Leasing / equipment-as-a-service (EaaS): spreads acquisition cost, standard for high‑capex industrial equipment; lowers enterprise procurement friction for factories and healthcare operators. Robots-as-a-Service (RaaS) / outcome pricing: providers charge per task, per shift or per throughput (e.g., pallets moved, rooms cleaned). This aligns vendor incentives to uptime and increases vendor capture of upside from improved autonomy. Support contracts and software subscriptions: updates, data pipelines and SDK marketplaces drive high‑margin recurring revenue; firms with attractive developer ecosystems (Boston Dynamics’ SDK experience, UBTECH’s education market) can monetize platform stickiness. Commercial pilots to date show customers preferring leasing and outcome pricing in logistics where labor substitution can be measured. Healthcare pilots (assisted living, patient transfer) show reluctance to accept pure capital purchase without robust service guarantees and regulatory clarity. Use cases, pilots and customer dynamics Key verticals and why they matter: Logistics & e‑commerce: standardized tasks (box handling, palletizing) and 24/7 shifts make outcome‑based contracts attractive. Agility and Figure target this first wave. Manufacturing & factories: cobot replacement in high‑cycle, low‑variance tasks — compatibility with existing conveyors and safety certifications are decisive. Boston Dynamics-backed integrators and system integrators can bundle robots into MRO contracts. Healthcare & facilities: high regulatory/insurance friction but attractive recurring revenue if safety and data protections (HIPAA, MDR/FDA) are met — expect slow, regionally staged rollout. Consumer & education: UBTECH, Xiaomi and Unitree are positioning lower‑cost units and SDKs to capture developer ecosystems and scale volumes. Pilot outcomes have consistently emphasized uptime, maintenance cadence and integration effort as the most common blockers converting trials to paid rollouts. Regulatory, certification and partnership hurdles Regulatory clearance (safety certifications, medical device approvals for healthcare) and insurance acceptance (worker comp, product liability) will compress vendor choice. Partnerships with integrators and service providers are essential — system integrators convert prototype demos into fleet operations and logistics providers (3PLs, large chain operators) provide the unit economics case studies enterprises require. Competitive positioning — a snapshot Company Scale readiness Technological sophistication Price-to-service ratio Tesla High High Uncertain — likely premium Xiaomi High Medium Low cost / high value Boston Dynamics Medium High High cost / premium service Figure Low–Medium High Premium R&D stage Apptronik Low–Medium High (actuators) Premium 1X Technologies Low–Medium Medium–High (actuators) Component supplier model Agility Medium Medium Favorable for logistics Unitree High (China scale) Medium Low cost UBTECH High (consumer channels) Medium Low cost / platform Sanctuary Low High Premium / R&D Conclusion — who wins by 2026? Winners will be those who control at least two of: manufacturing scale, component supply, and a persistent service/revenue engine. Tesla and Xiaomi can translate manufacturing scale into aggressive unit economics; Unitree and UBTECH can win volume and low‑price markets; Boston Dynamics and Agility can win enterprise deployments via service networks and integrator partnerships. The thin middle — many well‑funded startups that have great tech but outsourced manufacturing and single‑source actuators — will need to secure recurring revenue (RaaS, support contracts) or vertical partners fast to survive. In short: 2026 is not the year of the flashiest gait; it will be the year of repeatable logistics contracts, predictable service economics and supply chains that don’t break.