Selling the Shape: How Humanoid Makers Repositioned Their Bots for Healthcare, Home and Industry in 2025–26
Introduction Between 2025 and 2026 humanoid makers shifted from spectacle demos toward verticalized go-to-market playbooks designed to close pilots and win recurring revenue. This report synthesizes o...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
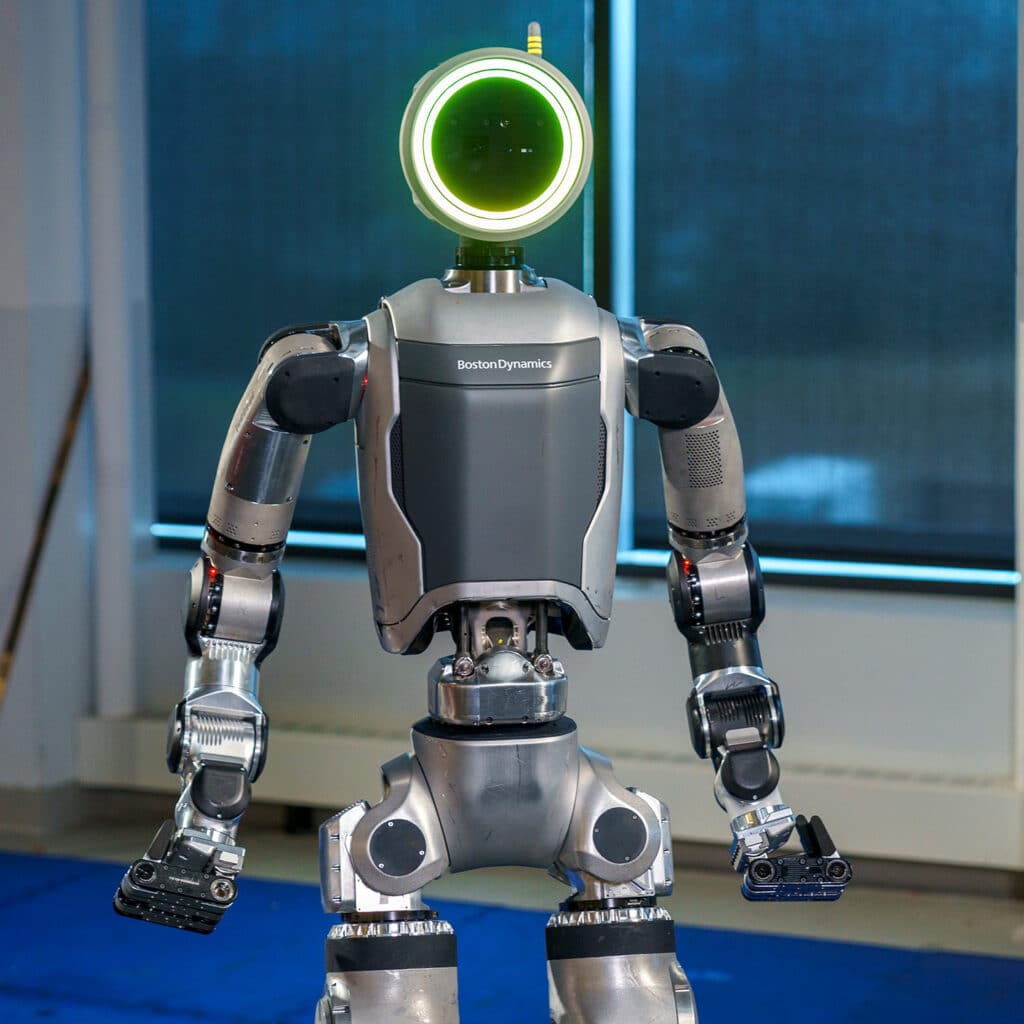
Introduction Between 2025 and 2026 humanoid makers shifted from spectacle demos toward verticalized go-to-market playbooks designed to close pilots and win recurring revenue. This report synthesizes observable tactics across five archetypes—healthcare/eldercare, consumer/home assistance, heavy-industry inspection, and logistics/manufacturing—comparing how Sanctuary AI (Phoenix), UBTECH, Xiaomi (CyberOne) and consumer-focused startups, Boston Dynamics/Atlas and Apptronik, and Figure AI/Tesla repositioned messaging, channel strategy and pricing to move from lab demos into contracts. How positioning maps to industries and use cases Companies tailored core claims to narrow buyer problems rather than emphasize general-purpose capability. The result: clearer pilot KPIs and faster procurement decisions. Healthcare / eldercare: Sanctuary AI (Phoenix) vs UBTECH Use cases: resident mobility assistance, routine vitals collection, supervised social engagement, and staff augmentation for repetitive transfers and fetch-and-carry tasks. Positioning: Sanctuary positioned Phoenix as "clinical adjuncts" that reduce caregiver physical load and fall risk by handling repetitive transfers and non-clinical patient interactions. UBTECH leaned into low-cost, service-oriented deployments—emphasizing reliability, easy sanitization and staff-facing operator controls. Pilots & results: company-reported assisted-living trials highlighted reduced caregiver time-on-task and improved response times for non-clinical calls. Operators reported productivity gains in the 10–25% range in early pilots where robots handled bed transfers and routine rounds (company-reported figures and pilot summaries). Buyer concerns & response: procurement and clinical leads prioritized infection control, proven emergency-fallback behaviors, and interoperability with EMRs. Both vendors adapted safety collateral—third-party risk assessments, IEC 60601 alignment language and patient-handling hazard analyses—to accelerate approvals by care home boards and clinical governance committees. Consumer / home assistance: Xiaomi CyberOne and domestic startups Use cases: household chores, telepresence, elder check-ins, voice-driven smart-home orchestration. Positioning: Xiaomi marketed CyberOne as an extension of its appliance ecosystem—emphasizing convenience, ecosystem integration and aspirational design. Smaller startups emphasized affordable, task-limited assistants (tidying, reminders, medication prompts) and distribution through consumer retail and appliance partners. Channels: consumer players used retail partnerships, appliance OEM bundling and subscription services for premium software features. Trials at assisted-living residences that allowed resident testing provided social proof back into retail campaigns. Industrial inspection & maintenance: Boston Dynamics/Atlas vs Apptronik Use cases: confined-space inspection, hazardous environment surveillance, repetitive maintenance preparatory tasks, and heavy-lift adjuncts for two-person jobs. Positioning: Boston Dynamics leaned on field-proven mobility and durability, selling Atlas as a platform for integrators and OD/ISVs to build solutions. Apptronik emphasized payload modularity and integrator-friendly APIs to land factory-floor pilots. Channels & sales motion: both relied heavily on systems integrators, VARs and operational trials with tier-1 industrial customers; direct sales were reserved for marquee enterprise accounts where long implementation cycles justified direct, consultative engagement. Logistics & manufacturing: Figure AI and Tesla Use cases: picking, kitting, palletizing, and autonomous material transport inside factories and fulfillment centers. Positioning: Figure AI and Tesla publicly framed humanoids as enterprise-first labor automation that displaces repetitive roles at scale. Messaging focused on throughput uplift (e.g., units-per-hour), deterministic ROI and integration with WMS/PLC systems. Pilot narratives: pilots were sold as short-cycle throughput studies with explicit baseline comparisons to human teams, enabling procurement to model payback periods. Channel strategy, pricing and procurement realities Across verticals three clear channel playbooks emerged: Direct enterprise sales: favored by Tesla and Figure AI for strategic, high-stakes factory deployments with long integration horizons. Integrator-led: used by Boston Dynamics, Apptronik and many healthcare deployments where hospitals and care homes required systems integration, clinical workflow design and compliance documentation. Retail / OEM distribution: adopted by Xiaomi and consumer startups bundling robots with appliances or home-install channels. Pricing communications revolved around three models: one-time capital purchases (common in industry), leasing (mid-market healthcare and facilities), and Robot-as-a-Service (RaaS) subscriptions (consumer and small care homes). Publicly visible industry benchmarks used in sales decks placed enterprise humanoids in the $100k–$400k hardware range with RaaS equivalents commonly modeled at $2,000–$15,000/month depending on payloads, sensors and included support—figures presented as ranges during vendor briefings and industry analyses. Safety, compliance and adapted pilot KPIs To win healthcare and industrial buyers vendors modularized safety artifacts: Hospital-ready collateral: infection-control protocols, EMR interfacing guides, clinical risk assessments and patient-handling SOPs. Industrial compliance: ATEX/IEC hazard class guides, tethered-fallback modes, and third-party force-limiting validations. Pilot KPIs shifted from capability demos to measurable operational outcomes tailored to buyers: Healthcare: reductions in staff time per transfer, call-response latency improvement, clinical incident rate per 1,000 resident-days. Industry: mean time between inspections, safety near-miss reduction, throughput delta vs human crews. Consumer: daily active use, retention rate, and appliance integration events per week. Collateral, campaigns and buyer psychology Successful campaigns reduced perceived risk via three tactics: Playbook collateral: downloadable “deployment playbooks” with step-by-step clinical governance checklists or factory integration timelines. Proof-point case studies: short, KPI-focused one-pagers showing pre/post metrics from pilots with anonymized buyers when NDAs prevented naming. Channel enablement kits: integrator training bundles, demo scripts, and liability/insurance templates to speed contracts. Marketing also employed phased messaging: hero demos for press and investor awareness; then verticalized microsites and tactical webinars featuring procurement and clinical stakeholders to address operational objections. Competitive comparisons and who wins which buyer Company Primary vertical Channel Buyer fit Sanctuary AI (Phoenix) Healthcare / general labor Direct + integrators Large care systems seeking clinical adjuncts with higher performance expectations UBTECH Eldercare / service Integrator + VARs Cost-sensitive care homes wanting lower-risk, operator-led deployments Xiaomi CyberOne Consumer / home Retail & OEM bundling Home consumers in smart-appliance ecosystems Boston Dynamics / Atlas Heavy industry Systems integrators Factories needing rugged mobility and integration partners Apptronik Inspection / maintenance Integrator-led Operational engineers needing modular payloads and APIs Figure AI / Tesla Logistics & manufacturing Direct enterprise Enterprises seeking scale automation and ROI modeling Framework: which marketing moves accelerated pilots-to-contracts Verticalized KPIs: quantifying outcomes that procurement models (time saved, incident reduction, throughput uplift). Compliance-first collateral: providing third-party safety validations and hospital-grade SOPs upfront. Channel enablement: arming integrators and VARs with playbooks, demo units and commercial templates. Flexible pricing: offering RaaS and short-term leases to shift budgets from capex to opex. Early adopter narratives: anonymized case-studies and co-marketing with pilot customers to reduce social risk. Conclusion By 2026 the most effective humanoid vendors had stopped selling general-purpose promise and instead sold measurable problem-solving packages tailored to buyer workflows. Whether through integrator partnerships in hospitals, OEM distribution into homes, or enterprise pilots with hard ROI targets on factory floors, the companies that translated demos into contracts did so by aligning safety proof, pricing flexibility and concrete KPIs with the language of procurement and clinical governance.