Selling the Shape: How Humanoid Makers Repositioned Their Brands for Healthcare, Home and Industry (2025–26)
Executive summary Through 2025–26 humanoid robotics vendors moved from spectacle to sales. Companies tailored not only product designs but entire go-to-market plays to match the constraints and procur...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
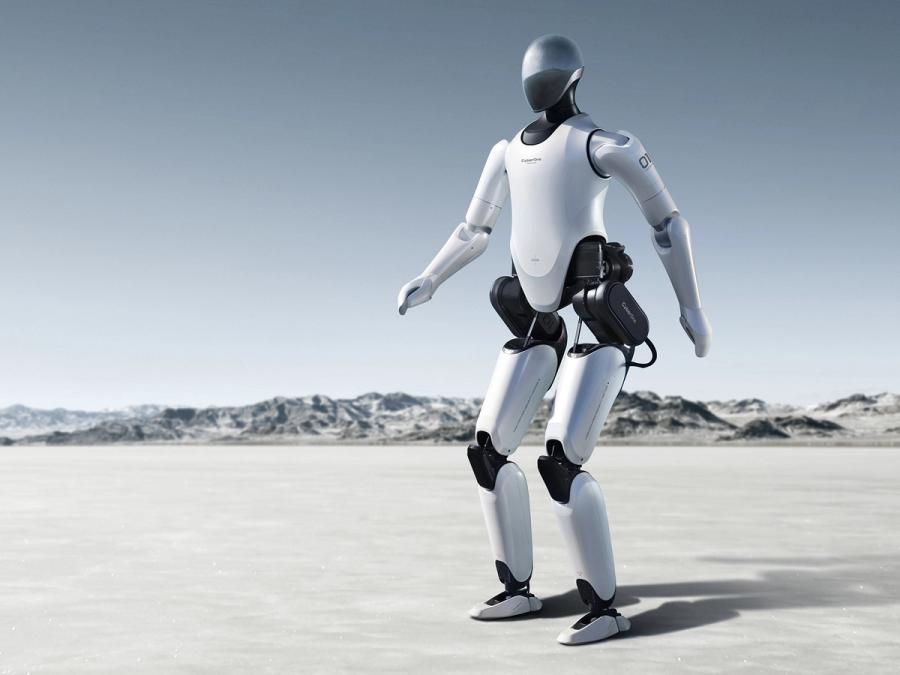
Executive summary Through 2025–26 humanoid robotics vendors moved from spectacle to sales. Companies tailored not only product designs but entire go-to-market plays to match the constraints and procurement rhythms of three distinct verticals: healthcare/eldercare, home/consumer-adjacent, and industrial logistics/manufacturing. The result was a bifurcation of narratives, certification investments, channel strategies and pricing models: empathy and safety for eldercare; retail and aspirational branding for consumer-adjacent; reliability, uptime and integrator partnerships for industry. This report analyzes how leading vendors—Sanctuary AI, Figure, UBTECH, Xiaomi/CyberOne, Agility, Apptronik, 1X, Tesla and Boston Dynamics—positioned themselves, the concrete tactics they used to win pilots and buyers, and which approaches showed evidence of traction by 2026. How messaging and regulatory posture diverged by vertical Vendors learned to speak the language of buyers. Two broad messaging frames dominated: Empathy + safety: Healthcare and eldercare buyers responded to narratives that foregrounded patient dignity, fall prevention, infection control and explainable autonomy. Productivity + uptime: Industrial and logistics buyers evaluated throughput, mean-time-between-failure, integration with WMS/ERP and total cost of ownership (TCO). Regulatory posture followed messaging. Healthcare-focused teams prioritized ISO 13485-aligned quality systems, CE medical device classification and early FDA engagement for software-as-a-medical-device (SaMD) pathways. Industrial-focused teams prioritized UL/CE safety standards, IEC 61508 functional safety work and third-party EMI/EMC certifications for factory deployment. Healthcare & eldercare: Sanctuary, Figure, UBTECH, Xiaomi/CyberOne Sanctuary and Figure explicitly steered their public messaging toward workforce augmentation and clinical safety. UBTECH and Xiaomi—each with consumer-device experience—deployed dual-track strategies: keep consumer footholds while building medical variants. Certification plays: Vendors invested in CE medical device certifications and IEC 62304 software lifecycle controls. By late 2025 several firms reported submitting pre-submission packages to regulators to clarify whether robotic therapy assistants would be considered medical devices or adjunctive consumer devices. Channel tactics: Partnerships with healthcare providers and regional staffing agencies became common. Vendors positioned robots as assistants to licensed staff—not replacements—reducing legal friction and easing union pushback in pilot sites. Product variants: “Clinical” SKUs with sealed surfaces, medical-grade sensors and detachable PPE surfaces were offered alongside base consumer models, enabling faster deployments in outpatient clinics and adult day-care centers. Home and consumer-adjacent: Xiaomi, UBTECH, Unitree Xiaomi leaned on retail distribution and experiential stores; UBTECH used education and enterprise customer bases to cross-sell consumer-adjacent services. Pricing cues were critical: Xiaomi emphasized an attainable, aspirational price point (low thousands of dollars in its public messaging) to differentiate from industrial-priced humanoids. Channel choice: Brick-and-mortar Mi Stores, online marketplaces and after-sales subscription services for updates and telepresence were primary channels. Story pivoting: When consumer-interest lagged, teams repackaged features (voice-based mobility, perception systems) for clinic therapy assistance and elder-engagement pilots—an explicit pivot to higher-trust institutional buyers. Industrial: Agility, Apptronik, 1X, Tesla, Boston Dynamics Industrial messaging concentrated on ROI and integration. Apptronik and 1X emphasized collaborative payloads and safety-rated stops to fit alongside human workers. Tesla and Boston Dynamics leveraged scale and brand recognition to sell a vision of fleet deployment. Integration channels: Systems integrators (SIs), white-label partnerships, and OEM deals were primary paths to market. Apptronik and Agility publicly emphasized SI networks and co-development deals for lane-level automation in warehouses. Pricing and models: RaaS (Robot-as-a-Service) and outcome-based contracts—charging per “pick-hour” or per-shift coverage—became dominant in logistics where capital budgets were constrained. Premium hardware sales persisted for specialized applications (precision assembly, hazardous environments). Concrete go-to-market tactics Certification as sales collateral: Vendors used UL/CE marks and medical-device pre-submission letters as trust signals in enterprise RFPs. Healthcare pilots that included a documented risk-management file and ISO-compliant QMS saw faster procurement cycles. Staffing partnerships: Multiple firms framed humanoids as tools bundled with staffing services—e.g., a regional eldercare operator contract that combined robot leasing with clinician training and staffing backups to address liability concerns. White-label & integrator networks: For factory automation vendors white-label agreements and SI certification programs accelerated deployments by placing humanoids inside existing automation stacks rather than selling direct. Trade-show strategy: Vendors bifurcated shows: CES and MWC for consumer buzz, RSNA and healthcare innovation forums for clinical credibility, and MODEX/Hannover Messe/A3 for industrial sales. Trade-show demos were paired with pilot-sales teams to convert leads into PoCs within 60–120 days. Pilot references & co-development: High-profile pilots were used as proof points. Vendors offering structured co-development (shared IP timelines, staged payments) reported higher pilot-to-deal conversion. Case vignettes From failed home launch to clinic therapy assistant Anonymized vendor “A” launched a consumer humanoid in late 2024 with emphasis on household companionship and voice interaction. Retail sales fell short of targets. The company refocused in 2025, creating a clinical variant with sealed surfaces, IEC 60601-inspired safety covers and a clinician training package. Within 9 months it secured three outpatient therapy pilots. The reframed narrative—“assistive mobility and repetitive-therapy extender”—reduced buyer resistance and shifted procurement from retail channels to clinical procurement teams. Pilot conversion improved from single-digit retail churn to a 28% clinic-pilot-to-deployment rate (company-reported). High-profile DC pilot accelerates chain adoption A second vignette involved a logistics-focused vendor that ran a six-week pilot at a national distribution center (anonymized). The pilot delivered a 12% increase in outbound picks per hour and a 7% reduction in peak overtime costs. Early results were packaged into a customer case study and used in direct enterprise sales and at MODEX; within six months the vendor signed three additional DCs through an SI partner. The combination of measurable KPIs, a conversion-guarantee clause and an RaaS pricing tranche proved decisive. Comparative messaging framework (Tesla, Figure, Sanctuary, Apptronik, Xiaomi) Company Primary vertical Core message Channel & pricing Regulatory focus Tesla Industry/Manufacturing Scale, cost elimination, fleet economics Direct enterprise, integrated into Tesla factories; hinted RaaS UL/CE, industrial safety integration Figure Enterprise/Service General-purpose automation for businesses Direct sales, enterprise pilots, co-development Early regulator engagement; safety standards for commercial use Sanctuary Healthcare & enterprise Human-centric augmentation, safety & ethics Partnerships with healthcare operators; subscription + deployment Medical-device pathways, ISO-aligned QMS Apptronik Industrial/collaborative Human-robot collaboration, payload flexibility SI networks, white-label, RaaS for pilots Functional safety, CE/UL work Xiaomi Consumer-adjacent Accessible intelligence, lifestyle augmentation Retail stores, online marketplaces, subscriptions Consumer-safety, optional clinical SKUs Effectiveness & outcomes (observed in 2026) By mid-2026 industry reporting and vendor disclosures indicated: Pilot-to-deployment conversion rates clustered by vertical: industrial pilots converted faster (often 20–30% where clear KPIs existed) than healthcare pilots (single- to low-double-digit rates) due to regulation and procurement cycles. RaaS and outcome-based pricing accelerated adoption in logistics and warehousing where buyers lacked upfront capital. Healthcare customers valued certification artifacts and co-developed workflows; vendors that invested in QMS and clinical pilots reported longer sales cycles but higher lifetime value after deployment. Retail consumer launches that lacked institutional fallback frequently underperformed; dual-track SKU strategies mitigated risk. “Buyers don’t want a prototype; they want measurable uptime and an audit trail,” said an SI executive working with multiple humanoid vendors in 2026, summarizing why certification and integrator relationships beat spectacle in procurement conversations. Conclusion Humanoid vendors that matched messages, certifications and channels to buyer needs made the most commercial progress in 2025–26. Healthcare buyers demanded proof of safety and workflow integration; consumers wanted approachable pricing and retail experiences; industrial customers wanted predictable ROI and SI-ready solutions. The winners were rarely the flashiest demos: they were the companies that built certification documents, secured co-development references, and packaged humanoids with services that removed risk for the buyer—turning pilots into paying deployments.