The Dealmakers Behind the Bipeds: Financing, Pricing and Partnerships Accelerating Humanoid Commercialization (2025–26)
Executive summary 2025–26 is the year commercial mechanics — not just capability — are determining which humanoid vendors scale. Pricing structures (outright sale, tiered SKUs, subscriptions, outcome-...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
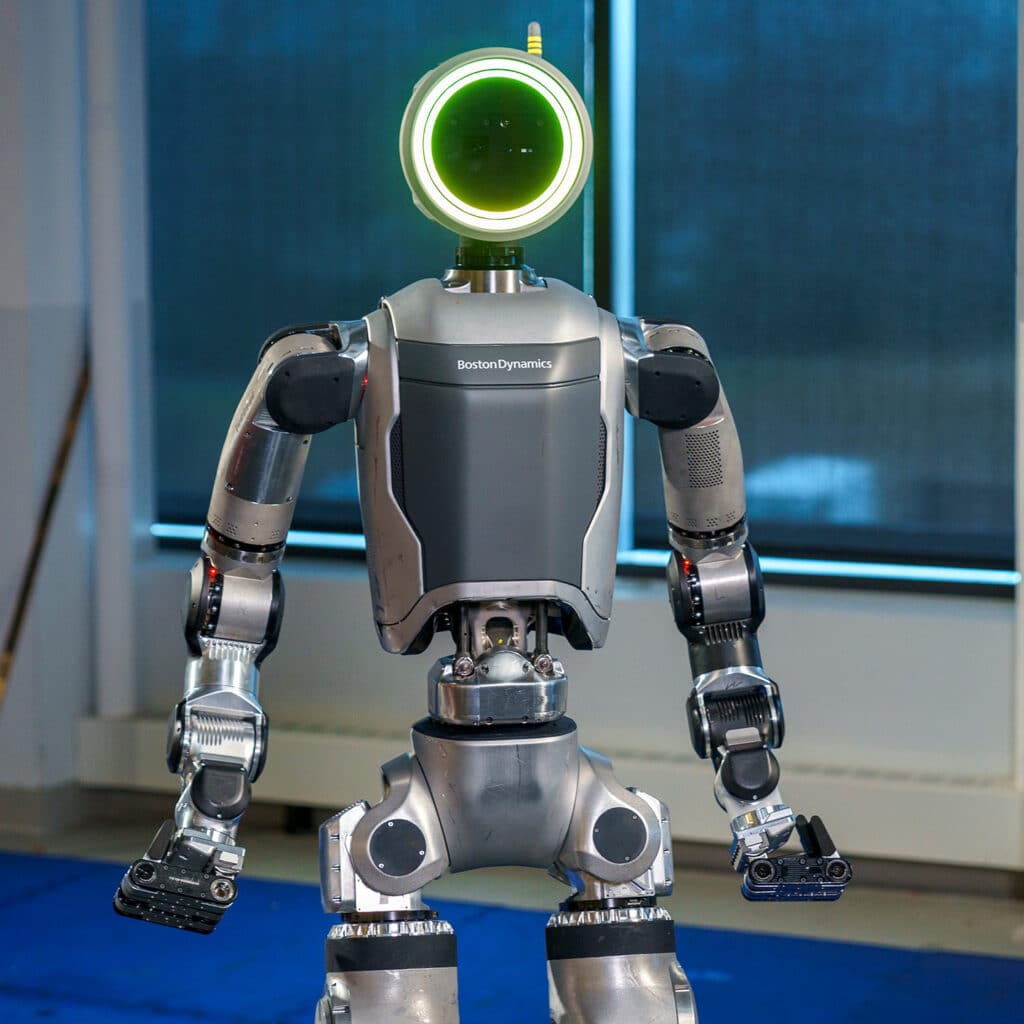
Executive summary 2025–26 is the year commercial mechanics — not just capability — are determining which humanoid vendors scale. Pricing structures (outright sale, tiered SKUs, subscriptions, outcome-based, leasing/RaaS), financing partners (third-party lessors, strategic investors, captive finance), and ecosystems of integrators, MES/WMS/EHR vendors and insurers now shape adoption curves as much as actuation and perception stacks. This report breaks down how vendors are packaging product, who pays for what risk during pilots and rollouts, and what buyers should check to avoid stranded investments. What customers are buying — use cases and industries Humanoids in 2025–26 are targeted at three commercial pockets: Logistics and warehousing: pallet-to-shipping dock movement, mixed-SKU pick-and-pack, night-shift automation where bipedal gait and human-form factor reduce rework on human-designed workstations. Healthcare and senior care: patient handling, repetitive logistics inside hospitals (linen, lab samples), and rehabilitation assistance where human form simplifies HRI and regulatory acceptance. Commercial facilities and enterprise services: security patrols, on-premise material handling, and demonstration deployments for retail and events. Customers adopt humanoids to solve labor shortages, reduce injury rates in ergonomic tasks, and compress throughput peaks without rewriting facility infrastructure — unlike fixed automation. Pricing strategies in practice Vendors now deploy a mix-and-match of five pricing levers: One-time unit sale: hardware-centric buyers (large integrators or corporate labs) paying a capital price, often with optional software licenses and support contracts. Tiered hardware SKUs: basic mobility-only units, mid-tier with manipulators and perception packs, and premium units with force-control hands and safety-certified stacks. Subscription software / Fleet Management System (FMS): recurring fees for orchestration, updates, teleops and analytics — typically $2k–$8k per robot per month in early enterprise deals (varies widely by scope). Outcome-based / throughput pricing: per-pick, per-delivery or per-hour-of-upside fees where customers pay a share of incremental revenue or cost savings — increasingly used in logistics pilots to align incentives. Leasing / Robot-as-a-Service (RaaS): monthly payments bundling hardware, software and SLAs to shift capex to opex and embed vendor-driven lifecycle services. How vendors use these levers Smaller entrants offer aggressive subscription or outcome-based pilots to de-risk customer commitments. Established industrial players and premium innovators lean on demo-driven premium pricing plus captive financing to absorb first-mover margins. Financing partners and risk allocation Three financing archetypes dominate rollouts: Leasing firms / third-party lessors: convert large order books to predictable cashflows; most vendors partner with local leasing houses to offer 36–60 month terms. Strategic VC / corporate financing: equity or structured credit from strategic investors (logistics firms, hospital groups) that want upside exposure and business-aligned KPIs. Captive finance arms: larger vendors (or parent companies) create in-house financing to smooth procurement cycles and maintain price discipline. Deals commonly allocate performance risk: vendors cover hardware failures and software patches; customers accept facilities modification cost and process change risk. Outcome-based contracts put more demand and market risk on vendors, raising the need for capital partners comfortable with operational variability. Partnership ecosystems Humanoid rollouts depend on an array of third parties: System integrators (SIs): handle localization, conveyor / shelving changes and safety fencing. Vendors with SI networks (Figure, Boston Dynamics partners) scale fastest. MES/WMS/EHR vendors: critical for production continuity; vendors now ship integration adapters for major WMS platforms to reduce SI billable hours. Safety certifiers and insurers: third-party certification (ISO/EN safety standards) and insurance brokers that underwrite operational liability are gating factors for healthcare and high-traffic deployments. Company playbooks — comparative snapshot Company GTM & Pricing Target Industry Channel / Financing Figure Enterprise bundles: hardware + FMS + on-site support; multi-year SLAs Healthcare, logistics Strategic investors, leasing partners Apptronik Full-system enterprise kits with integration support; tiered SKUs Manufacturing, warehouses SI partnerships, corporate finance Agility Robotics Pilot credits and revenue-share pilots; outcome-based for logistics Logistics, last-mile Third-party lessors, logistics FPs 1X Pilot-first model; shared revenue on throughput gains Healthcare, warehouses VC financing, revenue-sharing partners Tesla Internal deployment + enterprise licensing experiments In-house manufacturing, trial customers Corporate funding Xiaomi / UBTECH Low-cost tiers, channel partners in APAC; volume focus Retail, service, APAC enterprises Consumer financing, channel credit lines Boston Dynamics High-visibility partner pilots, demonstrator leasing to justify premium Construction, logistics, security Captive finance, SI network Case studies (anonymized) Logistics pilot — revenue-share model: a regional fulfillment center trialed 12 bipedal robots across two shifts. Vendor contributed 50% of hardware cost as pilot credit, the facility paid integration and retrofit. Contract: 12-month pilot, vendor receives 25% of measured incremental pick throughput revenue beyond a baseline. SLA: 95% availability target, penalties applied for missed uptime. Outcome: throughput rose 18% net of integration; vendor converted pilot into 60-unit RaaS contract with leasing partner co-funding to industrialize deployment. Healthcare deployment — enterprise bundle: a hospital network bought 8 units under a three-year bundle: one-time hardware, annual FMS subscription, and on-site training. Risk allocation: vendor retained maintenance and regulatory update obligations; hospital funded facility modifications and staffing for mixed human-robot workflows. Reimbursement support from a regional health authority covered 30% of pilot costs. "Early pilots consistently trade down-front unit receipts for operational data and repeatable integration templates — that data is the most valuable asset vendors can monetize in year two," said a procurement lead at a large retail chain (anonymized). Government, healthcare reimbursement and grants Public grants and procurement play a disproportionate role in de-risking pilots. EU and national innovation grants underwrite early-stage pilots and de-risk capital for vendors; U.S. defense and manufacturing grants have funded testbeds. In healthcare, reimbursement codes for remote patient handling and bundled payment models are emerging mechanisms that make hospital purchasing committees more receptive to multi-year bundles. Unit economics scenarios and recommendations At scale, break-even depends on the pricing mix: Hardware-sale heavy: faster cash collection but lower lifetime revenue; break-even requires >1,000 units and aftermarket margins (support, software) above 40%. Subscription / RaaS heavy: longer payback (24–48 months) but higher lifetime value and easier fleet upgrades; requires disciplined churn management and financing to cover early cash burn. Outcome-based pilots: high upside but highest capital strain; vendors without strong financing partnerships risk missed payout windows. Modeling example: a $100k unit sold with a $3k/mo software subscription yields break-even in ~18–30 months assuming 40% gross margin on software and a 20% annual support cost — moving to RaaS at $3k–$5k/mo extends payback to 24–42 months but increases LTV if churn stays Strategic recommendations For buyers (procurement checklist) Demand clear SLA definitions (uptime, mean-time-to-repair, spare parts lead times). Insist on integration scope and owner (vendor vs SI vs buyer) and an allowance for facility mods. Require safety certification evidence and insurance terms for operational liability. Prefer pilots with measurable KPIs and agreed baseline metrics to evaluate outcome-based pricing. Evaluate total cost of ownership across scenarios: capex + integration + downtime risk vs RaaS op-ex. For sellers (pricing playbook) Use pilot credits to buy data and repeatable SI templates, not to subsidize indefinite custom work. Bundle software/analytics to protect margins and create upgrade paths; tier FMS by functionality and scale. Secure financing partners early for outcome-based deals and RaaS; align investor horizons with contract payback. Standardize SLAs and carve out customer responsibilities to limit scope creep. Conclusion: in 2025–26 the winners will not only have stable locomotion and dexterous hands — they will have mastered capital markets, partner ecosystems and contract engineering that turn pilots into repeatable deployments.