Two-Legged Pitchbooks: How Humanoid Makers Reframe Their Robots for Warehouses, Factories and Homes
Two-Legged Pitchbooks: How Humanoid Makers Reframe Their Robots for Warehouses, Factories and Homes Humanoid robotics vendors sell essentially the same core capability — a bipedal, human‑sized mobile...
Published by The Humanoid Race
Archived source unverified — no source link is available. The claims, figures and quotations have not been checked against an available source. Retained for historical context, not presented as newly verified reporting.
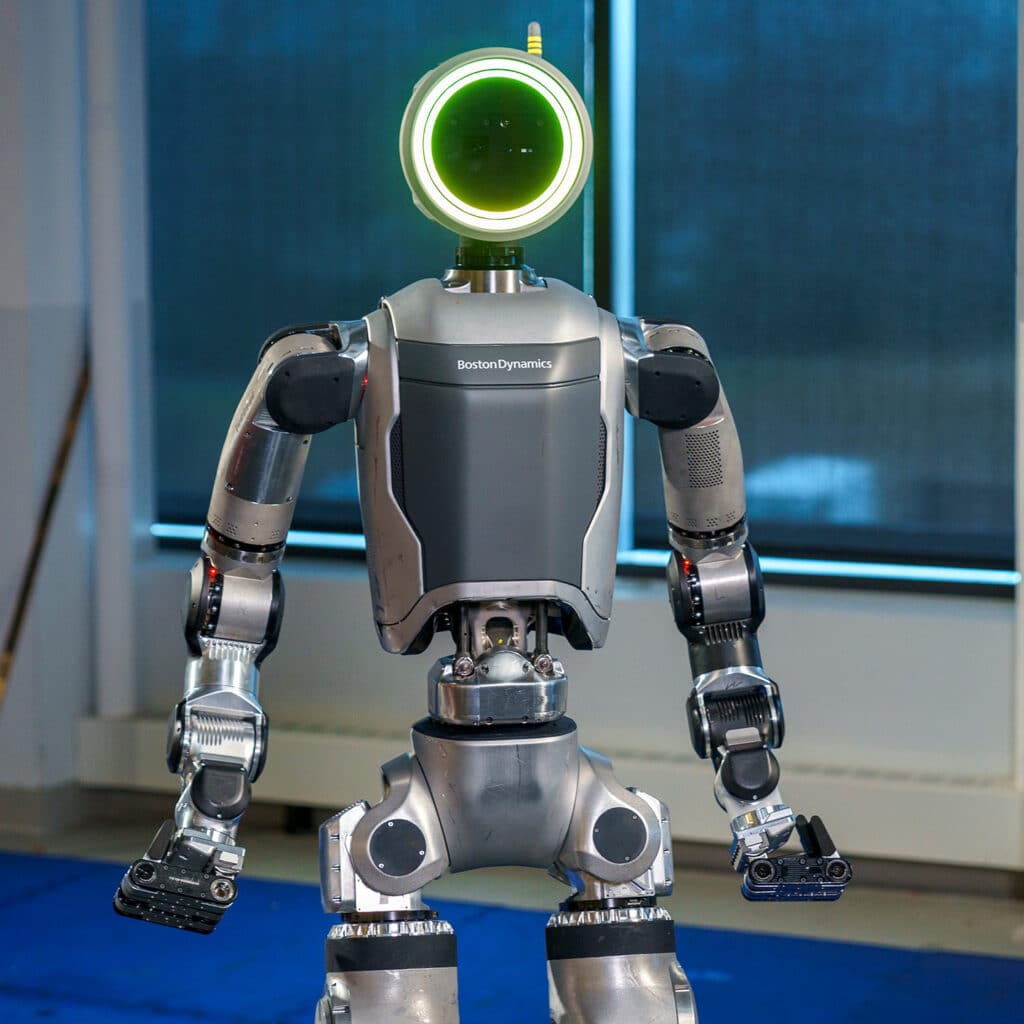
Two-Legged Pitchbooks: How Humanoid Makers Reframe Their Robots for Warehouses, Factories and Homes Humanoid robotics vendors sell essentially the same core capability — a bipedal, human‑sized mobile manipulator — into radically different buying committees. The result is a portfolio of differentiated go‑to‑market playbooks: consumer glamour and retail UX on one end, engineering‑first R&D halo projects on the other, and cost‑focused logistics automation in the middle. Below we analyze how leading firms position, price and channel similar hardware to win customers in warehouses, factories, healthcare and homes. Target segments and positioning archetypes Companies pursue one of several repeatable narratives when marketing humanoids: Consumer/brand halo: Emphasize personality, safety and UX for early adopters and retail sales (Xiaomi, UBTECH). Engineering halo + enterprise spin: Use a demonstrator (Atlas for Boston Dynamics; Tesla’s Optimus prototypes) to generate engineering credibility while selling different, pragmatic enterprise products. Logistics‑first automation: Position as warehouse workforce — repeatable tasks, clear ROI, metrics that procurement understands (Agility Robotics’ Digit). Industrial certified platforms + services: Emphasize safety certifications, uptime guarantees and service contracts for regulated industrial customers (Apptronik). Enterprise automation vs human‑replacement: Split narrative between augmentation and full automation, with companies like Figure and Sanctuary pitching enterprise workflows that minimize human labor costs. Company playbooks — messaging, channels and demo tactics Tesla (Optimus) Tesla’s external messaging oscillates between a long‑term consumer vision — a general‑purpose home/companion robot with mass‑market pricing eventually — and a near‑term factory pilot narrative. Public demos (AI Day presentations and prototype walkthroughs) serve two GTM goals: signal technical seriousness to engineers and prime manufacturing partners for internal pilot deployments. Tesla’s implicit channel is its own factories and energy/auto customers; it has not pursued traditional system integrators. Expect Tesla to continue using internal pilot results and high‑visibility demos rather than price‑list commerce. Boston Dynamics (Atlas, Spot, Stretch) Boston Dynamics maintains a bifurcated strategy: Atlas provides an R&D halo that keeps the company in headlines and in research partnerships, while commercial robots — Spot (quadruped) and Stretch (warehouse box handler) — are sold through direct enterprise sales, certified integrators and developer ecosystems. Spot's established customer base (utilities, construction, entertainment) and its publicized price point (Spot's list price was widely reported in the tens of thousands of dollars) let Boston sell CapEx with optional service agreements. Stretch is positioned specifically for parcel/warehouse handlers with integrator partners for conveyor and WMS integration. Agility Robotics (Digit) Agility frames Digit as a logistics product: end‑of‑aisle picking, pallet tasks and store re‑stocking. The company emphasizes defined KPIs (pick rate, cycle time, safety) and sells pilots framed as proof‑of‑value that feed into larger CapEx deals or RaaS conversion. Agility’s channel strategy leverages logistics integrators and 3PL partners to reach warehouses, with case studies used to push from pilot to fleet deployment. Apptronik (Apollo) Apptronik focuses on industrial certification and deterministic service contracts. Apollo — positioned as an industrial‑grade humanoid — is sold with structured support tiers, operator training and safety validation packages. Apptronik targets manufacturers and engineering teams, using demonstrations in collaboration with integrators and safety consultants to clear regulatory and ISO requirements. Figure, Sanctuary AI Both companies pitch enterprise automation. Their GTM emphasizes throughput economics and labor substitution: rigorous ROI models, staged pilots tied to existing workflows, and partnerships with staffing firms that help replace contingent labor with robot fleets. Their messaging carefully calibrates “automation” vs “augmentation” depending on customer sensitivity, particularly in healthcare where human replacement is fraught. Xiaomi, UBTECH These players pursue retail distribution, consumer UX and education markets. Xiaomi’s CyberOne (concept) and UBTECH’s humanoids focus on polished interfaces, app ecosystems and retail demos. Channels are consumer electronics retailers, online marketplaces and after‑sales service networks — low barrier to trial, high emphasis on looks, voice UX and safety markers for household use. Smaller/adjacent players (Unitree, 1X Technologies, Fourier) Unitree competes on affordability with low‑cost quadrupeds and sells through e‑commerce and reseller channels; Fourier (exoskeletons/rehab) and 1X Technology gravitate toward adjacent markets (medical rehab, defense) where biped capability or wearable robotics meet specific, regulated needs. Pricing models, financing and pilots Deal structures cluster into CapEx hardware sales with optional service contracts and subscription/RaaS models designed to lower buyer risk. Company Primary model Channel Pricing context Boston Dynamics CapEx + service Direct, integrators Enterprise list prices in high‑five to six figures for specialized platforms; Spot previously listed in the tens of thousands Agility Robotics Pilot → CapEx or RaaS Logistics integrators, 3PLs Apptronik CapEx + certified service tiers OEMs, system integrators Positioned as industrial‑priced — customers buy as capital equipment and budget service SLAs Xiaomi / UBTECH Retail CapEx CKD retail and online marketplaces Consumer price points (low thousands to tens of thousands) Typical pilot playbooks are short, tightly scoped programs: 4–12 weeks, clearly defined KPIs (throughput, downtime, safety incidents), acceptance tests and a path to expansion (fleet purchase, monthly subscription). Vendors use performance bands in proposals (e.g., “if unit achieves ≥X picks/hour under scenario Y, customer gets discounted fleet pricing”) to convert trials into multi‑year contracts. Industry use cases and customer evidence Warehouses and parcel handling: Humanoids promise access to human‑centric environments (stairs, narrow aisles). Agility sells this exact capability as its primary use case. Factories and assembly: Tesla and Apptronik emphasize human‑like manipulation and reach for assembly or inspection tasks that fixed automation cannot serve economically. Energy and inspections: Boston Dynamics’ Spot (quadruped) has concrete enterprise traction in inspections and remote sensing; the company uses those deployments to cross‑sell developer services and new platforms. Healthcare and eldercare: Here messaging shifts — vendors prioritize safety certifications, explainability, operator presence and dignity concerns. Sales involve clinical trials, liability reviews and longer procurement cycles. Channel partners, integrators and staffing firms System integrators, distributors and staffing firms are crucial funnels. Integrators convert a promising robot into a functioning line item by integrating with WMS, conveyors, safety systems and corporate IT. Staffing firms partner with robot sellers to offer “robot+human” workforce bundles: robots handle repetitive tasks while staff do exceptions. Vendors explicitly design pilot contracts to feed integrators — short technical pilots that prove the robot’s interface to incumbent systems. Risks, overpromising and expectation management “The most common sales failure isn’t a technical one — it’s a mismatch between headline capability and deployable value.” Across the industry vendors mitigate hype in three ways: conservative pilot KPIs; staged expansion clauses; and transparent failure modes in demo scripts. Companies that promise household companions and deploy industrial assistants risk credibility loss. Well‑managed vendors remove ambiguity in contracts (acceptance criteria, MTTR, uptime SLAs), use training and maintenance packages to protect customers, and keep product roadmaps separate from commercial offers. Competitive dynamics Competition is bifurcated: low‑cost, high‑volume consumer players (Xiaomi, UBTECH, Unitree) against high‑margin enterprise vendors (Boston Dynamics, Apptronik, Agility, Figure). The enterprise winners will be those that pair credible pilots, integrator ecosystems and predictable TCO models. For now the distinct narratives — engineering halo, logistics focus or retail UX — allow multiple companies to sell similar hardware without immediately colliding on price. For procurement teams, the decision calculus reduces to: Can the vendor show a repeatable pilot with clear KPIs? Is there an integrator capable of delivering a production‑grade installation? And does the commercial structure (CapEx vs RaaS, SLA terms) match the buyer’s risk appetite? Until humanoids prove consistent uptime and integration simplicity, GTM creativity — not just technical specs — will determine who produces scalable deployments.